
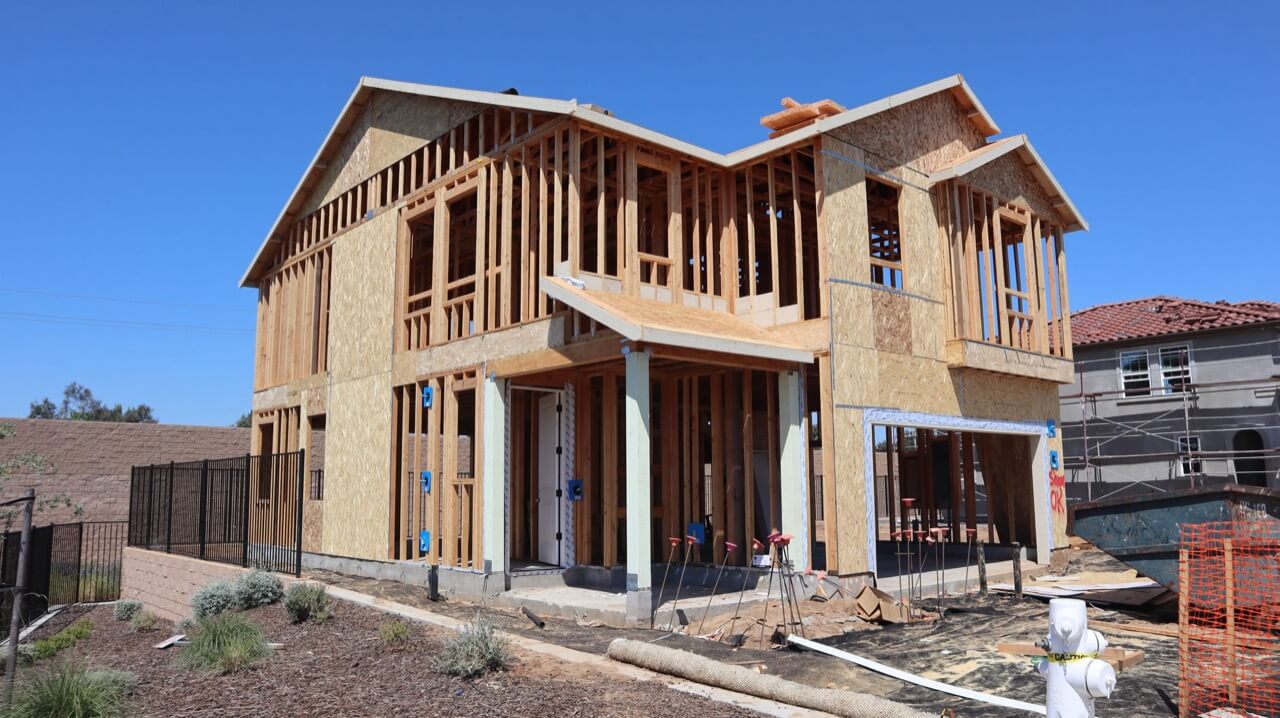
A construction loan rate lock is a way to hold pricing steady while a home moves through permits, break ground, draws, and final completion. The point is not to guess the market perfectly; it is to match the lock to the part of the project where rate movement would change the borrower’s total cost. A stronger lock can reduce uncertainty, but it may also cost more or require a longer timeline commitment.
On new construction, the lock decision usually depends on the loan program, the builder schedule, and how much time remains before the loan closes or converts to permanent financing. Locking too soon can leave the borrower exposed to extension fees if the build runs long. Locking too late can leave the borrower exposed to rate movement during the most sensitive part of the project. The practical goal is a written plan that fits the actual schedule, not the best-case schedule.
That is why borrowers compare the lock period, any extension terms, and the builder’s milestone dates before they commit. In a market with higher home values, those timing choices matter more because even a small rate change can move the monthly payment and the cash needed at closing.
Carlsbad’s home value is $1,361,646 (Zillow Research, July 2026), which makes timing decisions on a construction lock feel different here than in a lower-priced market. When the purchase price is this high, the cost of rate movement during a build can be meaningful enough that the lock strategy deserves the same attention as the floor plan.
The median home value in San Diego County is $791,600 (Census ACS 5-Year, 2023), while Carlsbad’s home value is $1,361,646 (Zillow Research, July 2026). That gap matters for a borrower deciding whether to lock early: the local price level is high enough that rate protection can affect the project budget more noticeably than it would in a cheaper market.
The same gap also explains why construction buyers in Carlsbad often need tighter coordination between the builder timeline and the loan timeline. A lock that fits the county average may not be enough runway for a higher-priced coastal build. I like to line up the lock strategy with the builder timeline so borrowers can see the cost tradeoffs in writing before they commit.
Building a new construction home gives you a distinct advantage in accumulating equity more quickly. When you invest in a newly built property, you often start with a fresh foundation and modern features that can appreciate in value. This means that as you make your mortgage payments, you might see your investment grow at a faster rate compared to purchasing an existing home. For borrowers, this can translate into a stronger financial position over time, allowing for more opportunities down the line. Overall, the process of building can be a strategic move for those looking to enhance their financial future.
Carlsbad homes are reaching pending status in 17 days (Zillow Research, July 2026), and price cuts share is 26.92% (Zillow Research, July 2026). For a construction borrower, that combination says the market is active but still pricing-sensitive, which raises the value of having a lock plan that can handle delays without forcing a rushed refinance or extension decision.
When the market moves this quickly, a borrower should assume the window between application, permit readiness, and closing can narrow faster than expected. That makes it more important to know whether the lock is protecting the construction phase, the permanent phase, or both.
Carlsbad’s rent is $3,617 (Zillow Research, July 2026), and the price to rent ratio is 31.37 (Derived (Zillow Research), July 2026). That means waiting for a build to finish has a real carrying-cost tradeoff: a borrower who rents while the home is under construction may be paying a large monthly amount while also trying to protect the future mortgage rate.
For a construction buyer here, the lock question is not just about rate movement. It is also about whether the cost of delay plus rent makes a longer lock or extension plan cheaper than trying to time the market more aggressively.
Carlsbad has 352 homes for sale (Zillow Research, July 2026) and 121 new listings (Zillow Research, July 2026). That tells a borrower there is ongoing supply coming to market, but not enough slack to assume a delayed build will be easy to replace with a cheaper alternative if the lock expires and pricing changes.
When inventory is limited relative to local prices, a borrower should treat the lock period as part of the purchase strategy, not as a back-office detail. The fewer affordable substitutes there are, the more expensive a missed expiration date can become.
San Diego County’s median household income is $102,285 (Census ACS 5-Year, 2023), and Carlsbad’s unemployment rate is 4.7% (BLS Local Area Unemployment Statistics, July 2026). Those numbers do not change the lock terms directly, but they do shape how much margin a borrower may have if the project runs long and the financing needs to absorb extra time or extension costs.
In a market with higher home values and a moderate job market, borrowers are usually better served by conservative timing assumptions than by a lock that only works if every milestone lands exactly on schedule.
Not always. In Carlsbad, the right time to lock depends on the builder’s schedule, the permit timeline, and how much price protection the borrower needs before completion. Because Carlsbad’s home value is $1,361,646 (Zillow Research, July 2026), a rate move can matter enough to justify early protection, but an early lock only helps if the build finishes inside the lock window.
The safer approach is to match the lock period to the realistic completion date, not the hoped-for one. That is especially important in a market where homes move to pending in 17 days (Zillow Research, July 2026), because local pricing can shift while the project is still underway.
Sometimes, but not if waiting creates extension fees, delayed closing costs, or a worse rate after the market moves. In Carlsbad, price cuts share is 26.92% (Zillow Research, July 2026), which signals that pricing is active enough that borrowers should not assume a later lock will automatically be better.
The decision comes down to the total cost of protection versus the risk of missing the window. With rent at $3,617 (Zillow Research, July 2026), waiting can also get expensive if the borrower is paying rent while the build runs long.
Compare the builder contract, the estimated completion date, the lock expiration date, and the extension terms. In Carlsbad, that comparison matters because the price to rent ratio is 31.37 (Derived (Zillow Research), July 2026), so a borrower may be paying meaningful housing cost while waiting for the home to finish. A short lock that saves money up front can become more expensive if the project slips.
The best lock period is the one that gives enough runway for the real schedule, not just the ideal one. That is true whether the borrower is using a construction-only structure or a construction-to-permanent structure.
Every figure comes from public data on Carlsbad, CA and San Diego County. Each one names its source and the month it describes, so you can check it yourself.
