
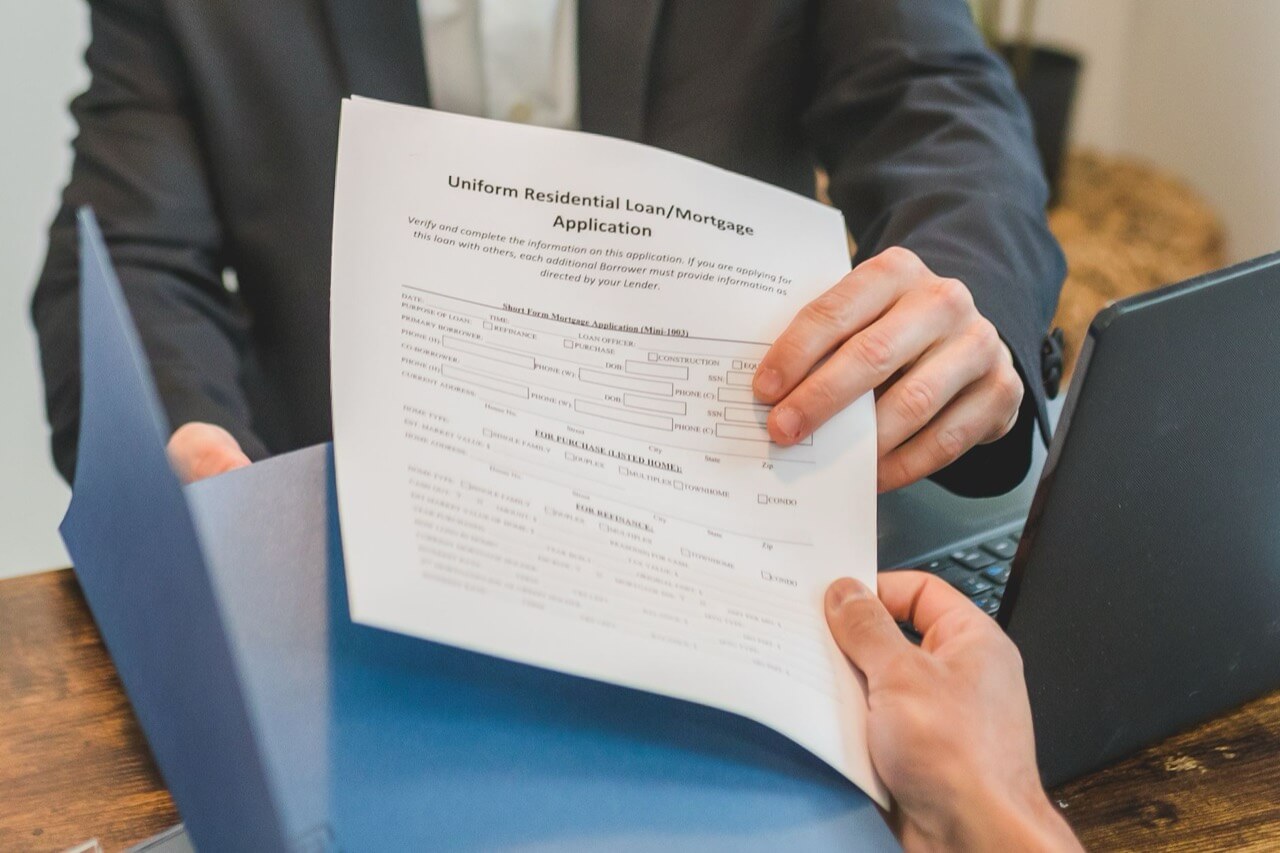
A self-employed mortgage is built for borrowers whose income does not fit a simple W-2 snapshot. That can include business owners, consultants, contractors, and professionals with deductions, seasonal revenue, or retained earnings. The job of the loan program is to translate the income story into a form underwriting can evaluate without pretending every business earns the same way.
Different programs look at income differently. Conventional loans may rely heavily on taxable income, while other options can give more weight to bank deposits, business cash flow, or alternative documentation. The right fit depends on credit, reserves, property type, and how clearly the borrower can document the business. In a high-cost market, the program choice matters because it affects how much payment room, flexibility, and certainty the borrower actually has.
That is why comparison matters before an offer is written. A loan that looks simple on paper can become harder once income documentation, pricing, and property limits are all lined up. For self-employed borrowers, the best outcome is usually not the biggest approval number; it is the structure that fits the file, the timing, and the way the business really operates.
The local home value is $934,169 in San Diego County, CA (Zillow Research, July 2026). In La Jolla, that kind of price means a self-employed borrower usually has to pay close attention to documentation, reserves, and monthly payment fit before choosing between conventional, bank-statement, or jumbo financing.
The price to income ratio is 9.13 in San Diego County, CA (Derived from Zillow Research and Census ACS 5-Year, December 2023). For a self-employed borrower in La Jolla, that tells you the market is asking a lot of household income, so a clean file and the right program can matter as much as the income itself. That is why I spend so much time comparing program structure and written pricing before anything moves forward.
Affluent borrowers often face unique challenges when navigating the mortgage market. Their tax situations can be quite complex, which is why common sense underwriting is essential. It's important to recognize that tax returns are not the sole method for qualification. In practice, we can utilize bank statement deposits, business profit and loss statements, and various other options to find the right fit for each individual. This flexibility allows us to better serve borrowers with diverse financial profiles.
The conforming limit 1 unit and the va county loan limit are both $1,104,000 in San Diego County, CA for 2026 (FHFA Conforming Loan Limits, 2026). For La Jolla buyers, that makes the line between a standard conforming file and a larger loan especially important, because it changes the financing lane before you even get to income documentation.
The fha limit 1 unit is also $1,104,000 in San Diego County, CA for 2026 (HUD CHUMS FHA Forward Mortgage Limits, 2026). In La Jolla, that means FHA can still be relevant at the one-unit level, but only if the rest of the file supports the program and the borrower wants the structure FHA offers.
Homes in San Diego County, CA reach days to pending in 20 days (Zillow Research, July 2026). For a self-employed buyer in La Jolla, that means the loan file needs to be organized early, because a slow documentation scramble can cost the home even when the income is strong.
The local rent is $3,008 and the price to rent ratio is 25.88 in San Diego County, CA (Zillow Research, July 2026). In La Jolla, that makes the rent-versus-buy decision more than a lifestyle choice: it is a cash-flow question, and self-employed borrowers often need a mortgage structure that keeps monthly housing costs predictable.
The median property tax is $5,542 and the effective property tax rate is 0.7% in San Diego County, California (Census ACS 5-Year, 2023). In La Jolla, those figures matter because the real monthly housing payment is more than principal and interest, and self-employed borrowers need to know the full carrying cost before deciding how much of the business income can safely support the loan.
Not always. A self-employed mortgage can be structured several ways, and some programs rely more heavily on bank statements or other alternative documentation than on taxable income alone. In La Jolla, that matters because the local price to income ratio is 9.13 in San Diego County, CA (Derived from Zillow Research and Census ACS 5-Year, December 2023), so the program has to fit both the income file and the market price.
Yes, if the loan amount stays within the right limit for the property type and program. For a one-unit home in San Diego County, CA, the conforming limit 1 unit, the fha limit 1 unit, and the va county loan limit are all $1,104,000 in 2026 (FHFA Conforming Loan Limits, 2026; HUD CHUMS FHA Forward Mortgage Limits, 2026). In La Jolla, that gives self-employed borrowers room to stay in a standard lending lane if the purchase price and down payment support it.
Renting can be a practical short-term move while a self-employed borrower gets documentation in order. In San Diego County, CA, rent is $3,008 and the price to rent ratio is 25.88 (Zillow Research, July 2026), so the choice depends on whether the borrower wants to keep cash flexible now or lock into ownership once the file is ready.
Every figure comes from public data on San Diego County, which includes La Jolla, CA. Each one names its source and the month it describes, so you can check it yourself.
