
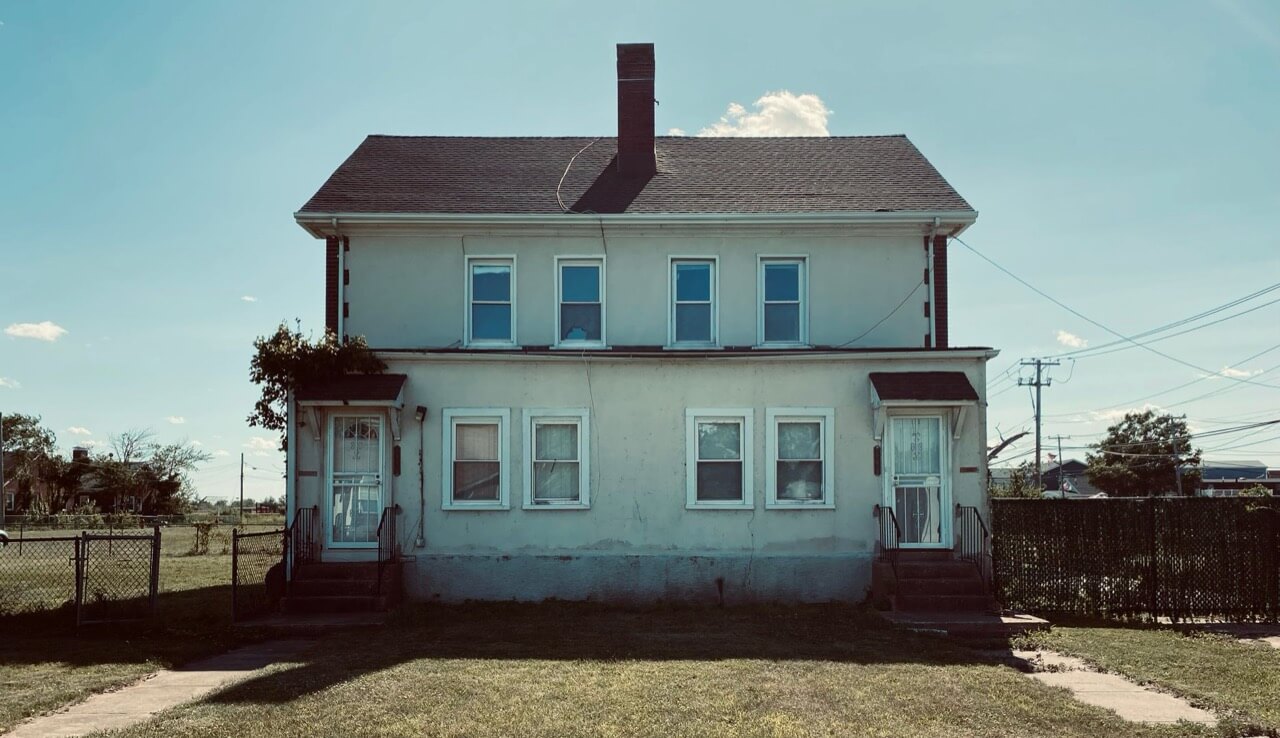
VA minimum property requirements are property-condition standards, not a judgment about the borrower. The program is looking for a home that is safe, sound, and sanitary enough to support financing. That means the house has to clear appraisal and condition review, and older homes can still qualify when maintenance is reasonable and any needed repairs are manageable.
For Temecula buyers, that distinction matters because the right offer is not just about winning the house. It is about choosing a property that can actually move through the loan without avoidable delays. A clean contract, realistic repair expectations, and a good read on the home’s condition can matter as much as price when you are working within VA guidelines.
The key is to evaluate the property early, before you commit to terms that only work if the appraisal comes back clean. That is especially important on older homes, where age alone is not the issue but deferred maintenance, safety items, and system problems can affect the file.
The median home value in Temecula is $768,913, according to Zillow Research, July 2026. That is the backdrop for every VA offer here: if a property needs repairs to meet program standards, the buyer has less room to overlook condition problems without affecting the deal.
Homes are going to pending in 26 days in Temecula, according to Zillow Research, July 2026, so buyers often feel pressure to act quickly. On older homes, that speed can be risky if you have not already thought through repair exposure and appraisal conditions. A fast offer is only helpful if the property can still satisfy VA requirements. When I’m working through a file like this, I like to compare the financing side in writing before the offer gets too far down the road.
I am dedicated to serving those who have served our country by providing them with the best mortgage structure available. This commitment means I focus on understanding their unique needs and ensuring they have access to the most suitable options. I believe that veterans and active service members deserve a mortgage experience that respects their sacrifices and supports their financial goals. By tailoring solutions to fit their circumstances, I aim to make the process as smooth and beneficial as possible for them.
Temecula has 547 homes in for-sale inventory and 30.4% price cuts share, according to Zillow Research, July 2026. Those figures suggest a market where pricing and condition are both under negotiation, which is exactly where VA property standards matter most. If a home looks like it may need work, the offer should leave room for repairs, credits, or a cleaner alternative property.
The rent in Temecula is $3,030 and the price-to-rent ratio is 21.15, both from Zillow Research, July 2026. That combination tells a buyer that ownership is expensive relative to rent, so condition risk matters even more: if a VA purchase is going to beat renting, the home has to be worth the added responsibility of repairs and appraisal follow-up.
Riverside County’s median home value is $510,300 and the median property tax is $4,189, according to Census ACS 5-Year, 2023. Those county-level costs help explain why a Temecula buyer should keep both monthly payment and repair budget in view. If an older home needs work to satisfy the VA file, the total cost picture can change quickly.
Yes. VA loans require the property to meet minimum property requirements so the home is safe, sound, and sanitary enough for financing. In Temecula, that matters because the median home value is $768,913, according to Zillow Research, July 2026, and a buyer cannot afford to ignore repair risk just to win the offer.
Yes, an older home can still work if it clears appraisal and condition review. Temecula homes often move quickly, with 26 days to pending and 547 homes in for-sale inventory, both from Zillow Research, July 2026, so buyers should sort out likely repair issues before they write. Age alone is not the problem; unresolved condition items are.
The VA county loan limit is $832,750 in Riverside County, according to FHFA Conforming Loan Limits, 2026. That is the key number for buyers who want to compare VA borrowing power with Temecula’s median home value of $768,913, from Zillow Research, July 2026. It means many homes here sit near the practical upper end of standard financing conversations, especially if repairs are also part of the deal.
Every figure comes from public data on Temecula, CA and Riverside County. Each one names its source and the month it describes, so you can check it yourself.
